Trust: Crypto & Bitcoin Wallet

Screenshots
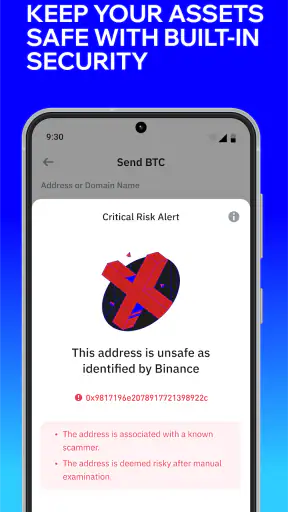
Details
- Rating
- 21.41K reviews
- Version
- 26.34.16
- Developer
- DApps Platform, Inc.
Analysis by Norviv
I found Trust: Crypto & Bitcoin Wallet most useful when I treated it as a personal finance tool rather than a shared household account. It is a free finance app from DApps Platform, Inc., built around self-custody: you hold responsibility for access to your digital assets instead of handing that responsibility entirely to an exchange. That distinction matters much more in everyday use than the polished wallet screens.
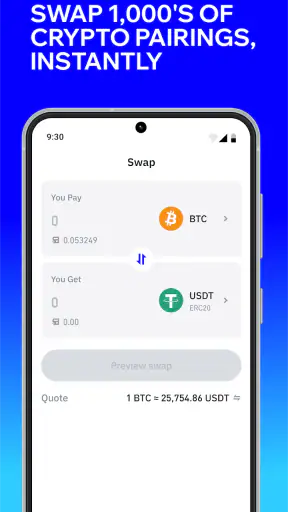
My first impression was that it tries to cover a lot in one place. You can use it to buy, sell, swap, and earn across multiple blockchain networks, while keeping the experience centered on one wallet application. That makes it appealing if you want to manage several kinds of crypto without jumping between unrelated apps. It also creates a learning curve, because every additional network, token, and transaction choice gives you another detail to check before confirming an action.
The app has a 4.5 average from around 2.5 million ratings, with over 50 million installs. Those figures suggest that Trust is not a niche experiment; it is a widely used wallet with a substantial audience. I still would not interpret popularity as protection from user error. In a self-custody wallet, a wrong address, an unsupported network, or a lost recovery detail can be far more serious than a normal app mistake.
Using Trust in a shared household
I would keep a shared household wallet separate from the routines people use to coordinate bills and plans. In this section, I’ll focus on a practical boundary: how family members can discuss a payment or review a public transaction detail without turning one person’s wallet into a shared device or shared responsibility. That distinction sets up the more personal question of who is actually ready to use it.
Why a personal wallet should stay personal
A realistic household example is a couple planning a holiday while one person occasionally buys cryptocurrency. It may seem convenient to install the wallet on a tablet used by everyone, then let both adults check balances or approve transactions. I would avoid that arrangement. A wallet is not like a shared shopping list: its security depends on keeping control of sensitive access and making sure the person initiating a transaction understands exactly what is being approved.
I would give each adult their own device and their own wallet setup. That creates a clear boundary between personal funds, browsing habits, and transaction decisions. If one person wants to show another a balance, a transaction history, or a public receiving address, that can happen deliberately without turning the whole wallet into a household object.
This approach is especially important when a phone or tablet is passed around. Even if the operating system has a screen lock, shared-device use can lead to accidental taps, copied addresses, or confusion about which account is currently open. Trust is designed for direct interaction with assets, so I would not leave it unlocked on a kitchen counter, family tablet, or work phone.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Setting boundaries before adding money
Before I would fund the wallet, I would decide what role it has in the household. Is it for learning with a small amount, holding a long-term personal position, or making regular swaps? Those are different jobs. A wallet used for experimentation should not automatically become the place where someone stores money needed for rent, groceries, or an upcoming bill.
The self-custody model also means that household trust has to be explicit. If two people want joint financial visibility, they should agree on what information is shared and what remains private. I would not copy recovery information into a family chat, save it in a shared notes app, or photograph it on a device that several people use. Convenience in this area can quietly remove the security advantage of self-custody.
There is another boundary that is easy to overlook: a wallet address is not the same thing as permission to spend from the wallet. Sharing a receiving address may be appropriate for a payment, but it does not make the other person a co-owner. I would explain that difference clearly to anyone in the household who is unfamiliar with crypto, especially if they are helping with a transfer.
Coordinating payments without sharing control
Trust can fit a household workflow when coordination happens outside the wallet and each user keeps control of their own account. For example, one person can send a public address through a carefully checked message, while the other confirms the network and amount before sending. I would repeat the address check immediately before approval rather than relying on an old copy from a previous transaction.
For a shared purchase, I would keep a simple written record of who paid, which asset was used, and which network carried the transaction. That is not a Trust feature; it is a practical habit. Crypto transfers can be difficult to reconcile later if several people use different assets or if one person assumes that a token on one network is interchangeable with the same-looking token on another.
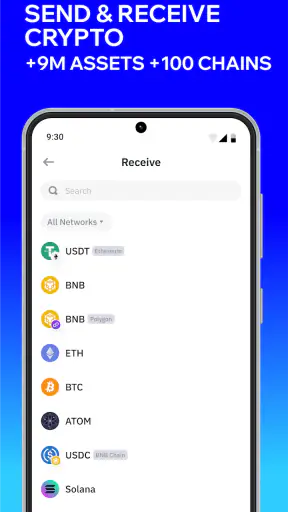
The app’s multi-chain focus is useful here but also demands discipline. Before swapping or sending, I would confirm three things: the asset, the network, and the destination address. A familiar token name does not remove the need for those checks. This is one of the most important non-obvious trade-offs in using a broad wallet: having many options in one interface saves app switching, but it gives the user more ways to choose incorrectly.
What coordination looks like in daily life
Imagine one household member receives payment in crypto and wants to convert part of it, while another person is tracking the family budget. Trust may help the first person manage the transaction, but it should not be treated as a complete budgeting system. I would record the conversion separately, note the date and amount, and keep household expenses in the finance tool already used for bills and planning.
If the family is simply sending money to one another, I would start with a small test transfer when the network or address is unfamiliar. That adds an extra step, but it is a sensible way to catch a copied address or an incorrect network before committing the full amount. The test should not create false confidence: the larger transfer still needs its own review.
I also prefer verbal confirmation for a high-value transaction, but not verbal sharing of secret recovery information. A useful confirmation sounds like, “I am sending this asset on this network to the address ending in these characters.” It should never involve reading a recovery phrase aloud in a shared room.
Age, trust, and who should use it
An Everyone content rating describes broad content suitability, not whether someone is prepared to manage digital assets. I’d look at whether a prospective user can explain the difference between a public address and private recovery information, and can pause when a request feels urgent. Those habits matter more than familiarity with crypto terminology, and they help clarify where a supervised introduction ends and independent use begins.
Everyone can download it, but not everyone should manage it
Trust carries an Everyone content rating, and its minimum operating-system requirement is version 9. That makes the app broadly accessible from a device-compatibility perspective. It does not mean that every age group is ready to control real digital assets. The difficult part is not opening the app; it is understanding irreversible transfers, network selection, recovery responsibility, and the consequences of approving a transaction.
I would be comfortable showing a teenager how a wallet works using public addresses and educational examples, but I would not hand over meaningful funds until they could explain the basic checks in their own words. A young user should know that a familiar logo or convincing message does not prove that a request is safe. They should also understand that an adult helping them should never ask for secret recovery information.
For younger children, I would skip real-money use entirely. Trust is not a substitute for a supervised learning environment, and I would not assume that a child understands the difference between viewing a balance and controlling it. The app’s broad age label describes content suitability, not financial readiness or family supervision.
Trusting the app is not the same as trusting a transaction
The name can encourage an emotional shortcut: users may feel that a trusted wallet makes every action safe. My experience leads to the opposite lesson. I can trust the app as a tool and still distrust an unexpected token offer, a rushed swap, or a message asking me to connect or transfer immediately.
This matters because self-custody changes where responsibility sits. With a traditional bank, a customer usually has a formal support path for a mistaken transfer or account-access problem. With a self-custody wallet, the user must be much more careful before confirming. I would choose Trust only if I accepted that responsibility and was willing to slow down when something looked unfamiliar.
For a household, I would create a short set of shared rules without sharing account secrets. No one approves a transaction while distracted. No one sends funds from a copied message without checking the address. No one installs a wallet from an unexpected prompt. No one treats a request for a recovery phrase as normal support. These rules are more valuable than simply telling family members to “be careful.”
Recovery planning needs a private conversation
One question many households have is what happens if the owner loses a phone. The answer depends on the wallet’s recovery process and on whether the owner has protected the relevant recovery information correctly. I would study the setup instructions inside the app, write down the required information offline, and store it somewhere private and secure rather than placing it on a shared device.
I would also decide whether anyone else needs to know that a wallet exists. That is different from giving them access. A trusted person may need general instructions for locating important documents in an emergency, but I would not turn recovery details into a casual family record. The goal is to balance continuity with the risk that too many people can discover or copy the information.
This is a point where another option may suit someone better. If a person is uncomfortable managing recovery information, frequently loses devices, or wants a conventional support relationship, a regulated exchange account or a traditional financial product may feel more appropriate. Trust is strongest for users who deliberately want self-custody, not for people who merely want a familiar banking experience with crypto branding.
What the app does well in practice
In practice, I value the way Trust brings several kinds of crypto activity into one place, but I would not treat that convenience as a reason to explore every option immediately. This section looks at a quieter strength: using the wallet first to observe and understand activity, then making a deliberate choice about whether to act. That measured approach leads naturally to a setup routine for users who want control without rushing.
A broad toolkit without constant app switching
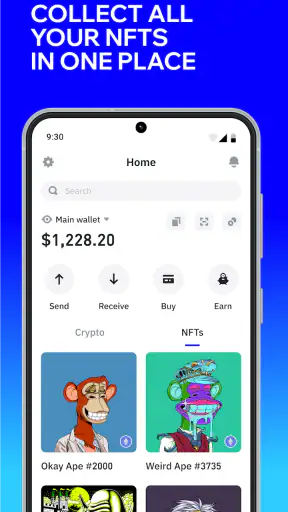
The main strength I noticed is concentration. Buying, selling, swapping, and earning are presented as parts of the same wallet experience, and the multi-chain design can reduce the need to maintain separate apps for every asset. For someone who already understands the difference between networks and wants one place to organize activity, that is genuinely convenient.
I also like the idea of separating observation from action. When I am checking a balance or reviewing activity, I do not need to make a transaction. I recommend building that habit deliberately: open the wallet to inspect first, then leave and return when you are ready to trade or send. It reduces the chance of making an impulsive decision just because the relevant button is visible.
Another useful habit is keeping a small transaction note outside the app. Record why a transfer was made, who requested it, and which network was selected. This becomes valuable when a household has several wallets or when a payment needs to be explained later. It also helps distinguish a deliberate action from an unfamiliar entry that deserves investigation.
Where the convenience becomes friction
The same range of functions that makes Trust versatile can make it feel busy. A newcomer may see unfamiliar assets, networks, swap choices, and earning-related options before they have learned the basic mechanics of sending and receiving. I would not explore every section on the first day. Start with wallet creation, security, receiving, and transaction review; only then consider more advanced actions.
Swapping is another area where the simple appearance of a button can hide several variables. The displayed result may depend on the asset pair, network, available liquidity, and transaction costs. I would review the final details rather than judging a swap by the headline amount alone. If I could not explain what I was receiving and which network was involved, I would cancel and research first.
Buying crypto inside a wallet can also look more straightforward than the underlying process really is. A user may still need to consider identity checks, payment-method availability, regional conditions, and the difference between purchasing an asset and controlling it afterward. I would treat the purchase screen as the beginning of a decision, not as proof that the transaction is automatically suitable.
How it compares with familiar alternatives
Compared with a centralized exchange, Trust gives self-custody a more prominent role. That can be a major advantage for someone who wants direct control and access to multiple networks from one wallet. The trade-off is that an exchange may feel easier for beginners who want account recovery, a familiar order interface, or a single platform handling more of the operational burden.
Compared with a basic single-chain wallet, Trust is broader. That breadth is helpful for users who hold different assets, but it may be unnecessary for someone who only needs a simple way to receive one type of cryptocurrency. A hardware wallet can be a better choice for long-term storage when the priority is keeping signing activity away from a frequently used phone, although it introduces its own setup and handling responsibilities.
For everyday budgeting, none of those crypto-focused choices replaces a normal bank account or expense app. I would use Trust for digital-asset activity and a separate system for household cash flow. Trying to make one wallet serve as a complete family finance hub would create confusion about balances, records, and responsibility.
My practical setup for a careful user
A careful setup is less about adding extra steps than deciding in advance what each step is meant to protect. I would separate device access, recovery information, and transaction review rather than relying on one vague promise to “be careful.” The following section turns that idea into a personal routine, including how I’d keep a first transaction small enough to learn from while still checking every detail.
Start small and learn the transaction path
I would install Trust only on a device I control, update the device first, and complete the wallet setup without an audience. I would read each security instruction slowly and avoid taking screenshots of sensitive recovery information. Once the wallet was ready, I would receive a small amount or use a low-stakes test rather than immediately transferring a large balance.
Before sending anything, I would identify the exact asset and network, paste or scan the destination only from a trusted source, and compare the visible address carefully. I would then check the amount and any displayed transaction cost. After sending, I would keep the transaction record and wait for the relevant confirmation rather than assuming that leaving the screen means the transfer succeeded.
For household use, I would give other people public information only when needed. A receiving address can be shared for a specific payment, but I would label it clearly and avoid keeping several addresses in a confusing group conversation. If someone else is helping, I would let them observe the process while retaining final control of the device and approval.
Keep advanced features behind a personal checklist
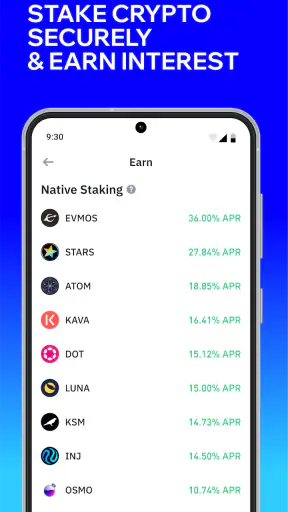
I would not use swapping or earning features simply because they are available. First I would understand the asset, the network, the expected result, the costs, and the risks of the particular action. A checklist is especially useful when the app makes advanced activity accessible from the same place as routine balance checking.
My checklist would include a pause before every irreversible action, a second look at the destination, and a written reason for the transaction. For a household, I would add a rule that no one acts on a message promising urgent profit or asking for immediate recovery details. These steps may feel excessive for a small transfer, but they become valuable habits before larger amounts are involved.
I would also keep the app current where the device supports its requirements. The current version is 26.34.16, and the app runs on operating-system version 9 or later. I would still review update prompts carefully and install software only through the normal official app-store route, because a fake wallet or imitation support message can be more dangerous than a missed feature update.
My household verdict
After using Trust as a self-custody wallet, I see it as a strong fit for an independent adult who wants buying, selling, swapping, and earning tools across multiple chains in one finance app. Its free price removes an initial barrier, and its large user base makes it easy to find general educational material. The developer, DApps Platform, Inc., has positioned the product for broad use, but the user still needs to bring careful habits.
I would recommend it to a household only with firm account boundaries. Each adult should control a separate wallet, shared devices should not become shared vaults, and coordination should happen through verified public details rather than shared secrets. For a young person, I would use it as a supervised learning subject before considering real funds. For someone who wants bank-like recovery or does not want to manage self-custody responsibilities, I would choose a different kind of service.
The app’s biggest practical lesson is that convenience and responsibility arrive together. Having many crypto functions in one place is useful, but it does not remove the need to understand each transaction. If I were recommending it to a friend, I would say: use Trust when you genuinely want control, begin with a small amount, keep the wallet personal, and pause at every network and address choice.
My final view is positive but deliberately cautious. Trust can be a capable central wallet for a knowledgeable user, especially one managing several assets without wanting a collection of separate apps. It is not a family account, not a household budget, and not a safety net for rushed decisions. The best way to use Trust is to share coordination, never share careless access, and treat every confirmed transaction as your own responsibility.
Frequently Asked Questions
01What is Trust Wallet, and what can I use it for?
Trust Wallet is a non-custodial cryptocurrency wallet for storing, sending, receiving, swapping, and managing digital assets. It supports many cryptocurrencies and blockchain networks, and it also provides access to decentralized applications through its built-in Web3 browser. Because it is non-custodial, you control the wallet’s private keys and recovery phrase rather than relying on a traditional bank or centralized exchange.
02Is Trust Wallet safe to use for cryptocurrency storage?
Trust Wallet includes security features such as encrypted private keys, biometric or passcode protection, and recovery-phrase backup. However, its security also depends heavily on how you use it. The recovery phrase should be written down and stored offline, never shared with anyone, and never entered into an unfamiliar website. Trust Wallet cannot recover funds if the phrase is lost or stolen, so users should be especially careful with phishing links and fake support accounts.
03Does Trust Wallet charge fees for transactions or swapping crypto?
Downloading and creating a Trust Wallet is generally free, but using cryptocurrency networks involves blockchain transaction fees, often called gas fees. These fees are paid to network validators and can change depending on congestion. Swapping assets may also involve a provider fee, spread, or other service charge shown before confirmation. The exact cost depends on the network, asset, transaction size, and service selected, so reviewing the final transaction details is important.
04Can I buy cryptocurrency directly through Trust Wallet?
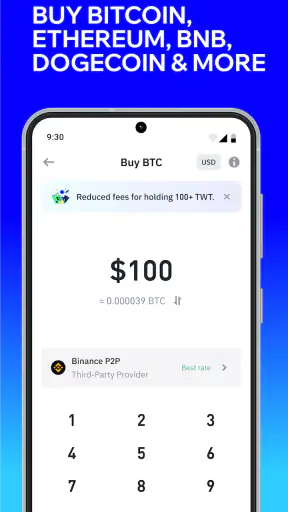
Trust Wallet may allow users to purchase selected cryptocurrencies through integrated third-party payment providers, depending on their country, payment method, and local regulations. Available options and fees can vary, and identity verification may be required by the provider. Buying crypto inside the app does not mean every asset is available everywhere. Before completing a purchase, check the quoted exchange rate, processing fee, minimum amount, and delivery conditions.
05What should I do if I lose my phone or forget my Trust Wallet password?
Trust Wallet does not hold your recovery phrase or provide a conventional password-reset service. If you still have the correct recovery phrase, you can restore the wallet on a compatible device and create a new local passcode. If the phrase is lost, forgotten, or exposed, access to the wallet may be permanently lost or funds may be at risk. Never trust anyone claiming to be support and asking for your recovery phrase or private keys.


